Brand experience in a physical store is measured through a combination of behavioural signals, perceptual data, and commercial outcomes. No single metric captures it fully. The most reliable approach triangulates what shoppers do, what they say, and what they buy, linking display interaction, dwell time, conversion rates, and satisfaction data to form a coherent picture of how a brand lands in-store. The sections below address the specific questions retail operators ask most when building a measurement framework for physical brand experience.
The signals that most accurately reflect in-store brand experience are behavioural, spatial, and perceptual. Behavioural signals include how long shoppers spend near a display, whether they pick up a product, and whether that interaction leads to a purchase. Spatial signals cover how shoppers navigate the store and which zones attract or lose attention. Perceptual signals come from what shoppers report feeling about a brand during or after the visit.
Together, these signals form a layered picture. A shopper who lingers at a display but does not convert is telling you something different from one who converts immediately without pausing. Brand experience is embedded in that gap. Foot traffic patterns reveal which areas of the store generate brand engagement and which are functionally invisible. Exit surveys and intercept interviews capture the emotional residue of the visit, whether the brand felt premium, accessible, trustworthy, or forgettable.
The most actionable signals are those that can be tracked consistently across visits and locations. Dwell time, interaction rate, and conversion at the fixture level are measurable without relying on shopper self-reporting, making them the backbone of any robust brand experience measurement programme.
Retailers quantify brand experience using a core set of shopper experience KPIs that span engagement, satisfaction, and commercial performance. The most widely used metrics include dwell time at branded fixtures, conversion rate from browsing to purchase, basket attachment rate, Net Promoter Score (NPS) collected in-store or post-visit, and brand recall measured through structured intercept research.
These brand experience metrics are most meaningful when tracked over time and benchmarked against a baseline. A one-off NPS score tells you little; a consistent upward trend following a display redesign tells you a great deal. Retailers operating at scale also track return visit frequency and average transaction value as indirect indicators of whether the brand experience is building loyalty rather than just driving one-time purchases.
For brands operating within third-party retail environments, such as pharmacy chains or department stores, additional metrics matter: share of fixture, adjacency quality, and compliance with agreed display specifications. These factors directly affect how the brand experience is perceived relative to competitors sharing the same retail floor.
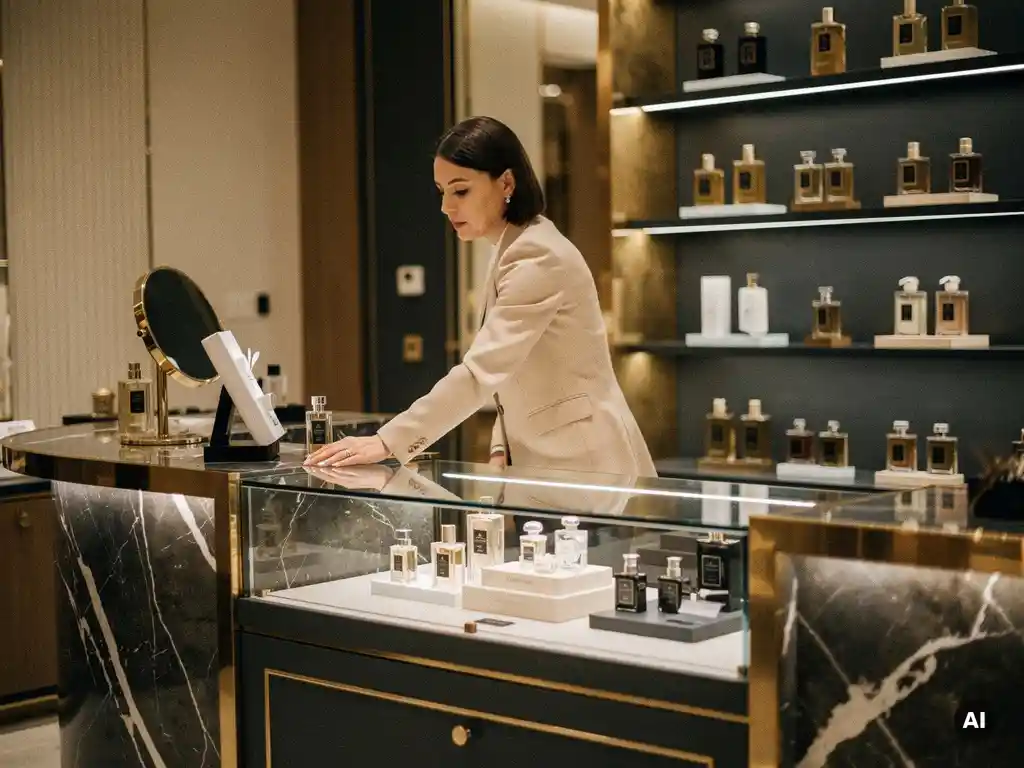
Display design has a direct and measurable effect on brand experience in physical retail. A well-executed display increases dwell time, improves product interaction rates, and reinforces brand perception through material quality, colour, and spatial hierarchy. Poorly designed displays, regardless of product quality, reduce engagement and can actively damage brand perception by signalling low investment or inconsistency.
The relationship between design and measurable outcomes is not abstract. Fixture height, sightline positioning, lighting, and material finish all influence whether a shopper stops, engages, and forms a positive brand impression. Bespoke retail display design that is built around a specific brand brief consistently outperforms generic or repurposed display solutions on engagement metrics.
Rapid prototyping and in-store testing allow brands to validate design decisions before full rollout. Testing two fixture variants in live retail environments and measuring dwell time, interaction rate, and conversion against each produces data that removes guesswork from design investment decisions. This approach treats display design as a measurable commercial lever, not a purely aesthetic one.
Shopper satisfaction and brand experience are related but distinct measures. Shopper satisfaction reflects whether the visit met functional expectations: was the product available, was the store easy to navigate, was the queue manageable? Brand experience reflects something deeper, whether the interaction with a brand's in-store presence created a positive emotional impression that extends beyond the transaction itself.
A shopper can leave satisfied without having had a meaningful brand experience. They found what they needed, paid, and left. Conversely, a shopper can have a strong brand experience in a category they did not purchase from that visit because the display, the product story, or the sensory environment left a lasting impression that influences future behaviour.
For multi-brand retailers, this distinction matters operationally. Satisfaction scores reflect the store's performance. Brand experience scores reflect how individual brands within that store are landing with shoppers. Brands that invest in distinctive, well-executed in-store environments tend to score higher on brand experience metrics even within environments where overall satisfaction is moderate. The two measures should be tracked separately and reported to different stakeholders accordingly.
Multi-store operators can track brand experience consistently by standardising measurement inputs across locations and establishing a repeatable audit and reporting cadence. This requires agreeing on a fixed set of brand experience metrics, dwell time, NPS, conversion rate, display compliance, and collecting them using the same methodology at every site, removing location-specific variation from the data.
The practical challenge for multi-store operators is compliance. A brand experience programme is only as reliable as the consistency of its in-store execution. If display specifications are not maintained uniformly across locations, the measurement data reflects operational inconsistency rather than genuine brand experience variation. Scheduled installation checks, photographic compliance reporting, and rapid response maintenance protocols are therefore prerequisites for meaningful cross-store comparison.
Centralised dashboards that aggregate store-level data allow operators to identify which locations are delivering strong brand experience outcomes and which are underperforming. This enables targeted intervention, whether through display refresh, staff training, or fixture repositioning, rather than blanket changes applied across the entire estate without diagnostic insight.
A brand should consider redesigning its in-store experience when data shows sustained decline across two or more core brand experience metrics, or when a structural shift in shopper behaviour makes the existing display format misaligned with how shoppers now engage with the category. Isolated dips in a single metric rarely justify a full redesign; persistent underperformance across engagement, satisfaction, and conversion does.
Specific data triggers that indicate a redesign is warranted include: dwell time falling consistently below category benchmarks, NPS scores declining quarter-on-quarter without an operational explanation, conversion rates at the fixture level dropping despite maintained footfall, and brand recall scores weakening in post-visit research. Any one of these signals warrants investigation. A combination of two or more signals across multiple locations is a clear case for redesign.
Brands should also treat external context as a data input. A competitor's significant in-store investment, a shift in the retailer's own store format strategy, or a change in the brand's own product range can each make an existing display solution structurally obsolete, even if historical performance metrics were acceptable. Proactive redesign based on forward-looking context often delivers stronger outcomes than reactive redesign triggered by declining numbers.
Pivotal works with brands to design, manufacture, and install in-store environments that are built from the outset to deliver measurable brand experience outcomes. As a full-service retail design partner, Pivotal brings together creative design, rapid prototyping, and compliant installation to ensure that what is agreed in the brief is what shoppers encounter in-store, consistently, across every location.
If your brand is ready to build an in-store experience that performs as well as it looks, contact Pivotal to discuss your next project.
Most brands begin to see statistically reliable trends after 8–12 weeks of consistent data collection, provided measurement inputs are standardised across locations from the outset. A shorter window can produce misleading results due to seasonal fluctuations, promotional periods, or early novelty effects from a new display. For the most actionable insights, plan your measurement programme around a minimum of one full trading quarter before drawing conclusions or making significant design changes.
The most common mistake is relying on a single metric — typically NPS or sales conversion — and treating it as a complete picture of brand experience. No individual metric captures the full story; a brand can post strong conversion numbers while quietly eroding emotional brand perception among non-purchasing shoppers. A robust measurement framework always triangulates at least three signal types: behavioural (dwell time, interaction rate), commercial (conversion, basket value), and perceptual (satisfaction scores, brand recall).
In third-party retail environments such as department stores, pharmacies, or grocery multiples, focus your measurement on the variables you can directly influence: fixture-level dwell time, interaction rate, display compliance, and share of fixture relative to competitors. Supplement these with post-visit intercept research or digital follow-up surveys that isolate your brand's impression from the overall store experience. Maintaining strict display compliance through scheduled audits and photographic reporting is especially critical here, since inconsistent execution will distort your data and undermine any meaningful cross-location comparison.
Yes — a lightweight but effective measurement programme can be built around three low-cost inputs: timed observation studies to capture dwell time and interaction rates, short exit intercept surveys (five questions or fewer) to gather perceptual data, and fixture-level sales data pulled from retailer EPOS systems. Start with two or three pilot locations rather than attempting full-estate measurement immediately, and establish a consistent baseline before testing any display changes. The discipline of consistent methodology matters far more than the sophistication of the tools at this stage.
Brand experience data works best as a shared commercial conversation rather than a one-sided reporting exercise. Brands should present fixture-level engagement and conversion data alongside category benchmarks to give retail partners context, and frame insights around joint outcomes — such as category growth and shopper satisfaction — rather than brand-specific performance alone. Agreeing upfront on which metrics will be tracked and reported, and at what cadence, prevents disputes over methodology later and builds the kind of collaborative relationship that makes it easier to secure better fixture placement and compliance support.
Staff interaction is one of the most powerful but most inconsistently measured variables in in-store brand experience, particularly in beauty, pharmacy, and premium lifestyle categories where assisted selling is common. A well-designed display can be significantly undermined by staff who are unfamiliar with the brand's product story or positioning. Measuring staff-influenced interactions separately — through mystery shopping, assisted-sale conversion tracking, or post-visit surveys that ask whether shoppers received help — allows brands to isolate the contribution of human touchpoints from the physical environment and target training investment where it will have the greatest impact.
Build your framework around outcomes rather than specific tools, so that as sensor technology, AI-powered analytics, and in-store data platforms evolve, your core metrics — dwell time, conversion, satisfaction, brand recall — remain consistent even if the collection methods change. Avoid locking your programme into proprietary technology that cannot export raw data, as this creates dependency and limits your ability to benchmark across platforms. Reviewing your measurement toolkit annually against emerging retail tech, while keeping your KPI definitions stable, gives you both adaptability and the longitudinal data continuity needed to spot genuine trends over time.