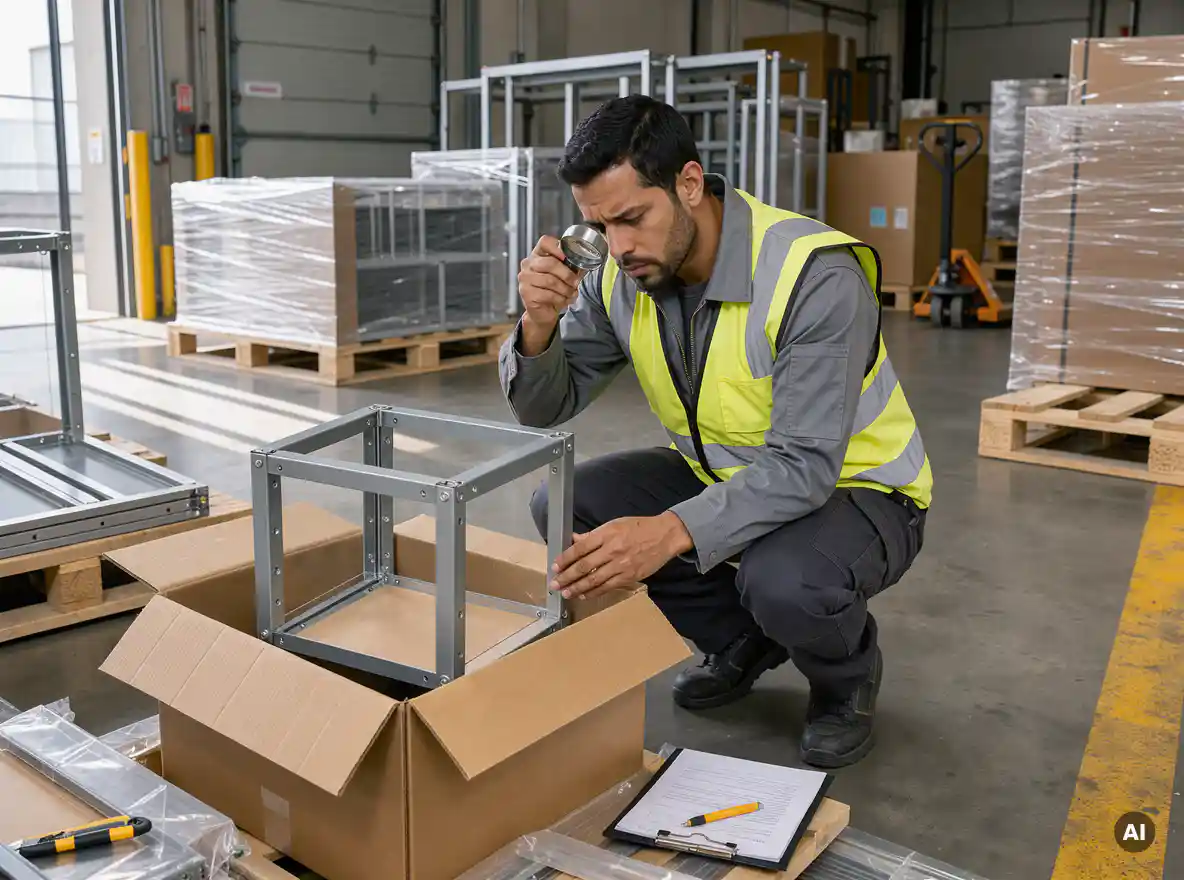
Receiving clerk inspecting a retail display unit with a loupe beside a delivery clipboard in a pallet-filled loading bay
How do you find vendor fraud in retail receiving?
Short shipping and phantom deliveries drain retail margin. Spot the red flags and use three-way matching to catch vendor fraud.

Vendor fraud in retail receiving is found by reconciling every inbound delivery against the purchase order, verifying quantities and quality at the dock, and analysing receiving data for anomalies. Detection depends on separating the duties of ordering, receiving, and payment, and on treating discrepancies as evidence rather than clerical errors. This article sets out the common schemes, warning signs, verification steps, analytical methods, and preventive controls that underpin effective retail loss prevention.

What are the most common vendor fraud schemes at receiving?

The most common vendor fraud schemes at receiving are short shipping, substitution of inferior goods, phantom deliveries, and false invoicing for goods never supplied. Each exploits the gap between what a purchase order specifies and what physically reaches the dock. Collusion between a supplier and a receiving employee makes every scheme harder to detect.
Understanding how each operates helps loss prevention teams target the right checks:

  • Short shipping: The vendor invoices for the full order but delivers fewer units or cases than agreed.
  • Substitution: Lower-grade, counterfeit, or near-expiry products replace the specified items while the invoice reflects the original specification.
  • Phantom deliveries: Goods are recorded as received, or invoiced, when no delivery took place, often with an insider signing the paperwork.
  • Duplicate or inflated invoicing: The same delivery is billed twice, or unit prices rise above the contracted rate.
  • Pallet and packaging padding: Full-looking pallets conceal empty layers, hollow cartons, or filler material.

These schemes rarely appear in isolation. A vendor that substitutes goods on one line often shorts another, so a single discrepancy warrants a wider review of that supplier's recent deliveries.

What red flags suggest a delivery is fraudulent?

Red flags of a fraudulent delivery include unscheduled arrivals, sealed cartons with inconsistent weights, paperwork that does not match the purchase order, and pressure on staff to sign without inspection. Any single indicator may have an innocent explanation, but a combination should trigger a full audit of the consignment before acceptance.
Receiving teams should watch for the following signals:

  • Deliveries arriving outside agreed windows or without a booking reference.
  • Drivers who discourage counting, hurry the sign-off, or offer to leave goods unattended.
  • Tampered seals, repacked cartons, or mixed batch codes within a single pallet.
  • Delivery notes lacking purchase order numbers, or listing quantities that round suspiciously.
  • Recurring small shortages from one vendor that individually fall below investigation thresholds.
  • Invoices that reach accounts payable before goods are physically received.

Behavioural patterns matter as much as documents. A receiving employee who consistently handles one vendor's deliveries alone, or who resists rotation, presents a collusion risk that process controls should address.

How do you check deliveries against purchase orders?

Checking deliveries against purchase orders requires a three-way match of the purchase order, the delivery note, and the physical goods before any invoice is approved. Staff should count and inspect items blind, meaning without first viewing the expected quantities, then compare results against both documents and record every variance.
A disciplined receiving procedure follows these steps:

  1. Confirm the booking: Verify the delivery against the scheduled appointment and the open purchase order.
  2. Inspect the vehicle and seals: Record seal numbers and note visible damage or tampering before unloading.
  3. Count blind: Have the receiver count cartons and units independently, then compare with the paperwork.
  4. Sample the contents: Open a defined proportion of cartons to check product, specification, batch, and expiry dates.
  5. Record variances immediately: Annotate the delivery note, photograph discrepancies, and obtain the driver's countersignature.
  6. Release the invoice only after matching: Accounts payable should pay against confirmed receipt, not against the vendor's claim.

Photographic evidence and time-stamped receiving logs strengthen any later dispute and discourage opportunistic behaviour, since vendors know deviations will be documented.

How can data analysis reveal vendor fraud patterns?

Data analysis reveals vendor fraud by comparing receiving records, invoices, and inventory movements over time to expose statistical anomalies that manual checks miss. Consistent shortage rates, unusual price variance, and invoice timing outliers all point to fraud. Trend analysis across vendors, sites, and receiving staff isolates where losses concentrate.
Effective analysis focuses on a small number of high-value measures:

  • Variance rate by vendor: Rank suppliers by shortage and damage rates and investigate those that sit consistently above peers.
  • Receiver and vendor pairings: Identify combinations where discrepancies cluster, which can indicate collusion.
  • Price and quantity drift: Flag invoices that deviate from contracted unit prices or exceed order quantities.
  • Invoice sequencing: Detect duplicate invoice numbers, round-value invoices, and billing just beneath approval thresholds.
  • Stock-to-sales reconciliation: Compare received volumes with sell-through and shrinkage to find goods that were paid for but never reached the shelf.

Exception reporting should be reviewed on a fixed schedule, with clear ownership and escalation routes. Analysis only protects margin when its findings lead to action, whether that is vendor scorecards, chargebacks, or contract review.

Which controls stop vendor fraud before it happens?

The controls that stop vendor fraud before it happens are segregation of duties, vendor vetting, mandatory three-way matching, receiving staff rotation, and secured, camera-monitored dock areas. Prevention works by removing the opportunity and raising the likelihood of detection, which deters most fraud before any loss occurs.
Retail loss prevention teams should embed these safeguards as standing policy:

  • Segregation of duties: No individual should order, receive, and approve payment for the same goods.
  • Vendor onboarding checks: Verify company registration, bank details, and references, and re-verify when payment details change.
  • Controlled dock access: Restrict entry, schedule deliveries, and use CCTV across receiving bays.
  • Rotation and audits: Rotate receiving staff and run unannounced spot counts on high-risk vendors.
  • Whistleblowing channels: Provide a confidential route for staff to report concerns.
  • Contractual remedies: Include audit rights, penalties for non-compliance, and clear dispute procedures in supplier agreements.

Loss prevention extends beyond the dock to the shop floor, where displays and fixtures are exposed to theft and damage. Well-specified, durable fixtures with proper retail maintenance keep merchandise secure and presentable throughout the product life cycle.

How Pivotal helps with retail loss prevention

Pivotal supports retail loss prevention by designing, manufacturing, installing, and maintaining in-store fixtures and displays that protect stock and sustain brand presentation. Because Pivotal's own employed fitters carry out installation, brands retain control from concept through to the shop floor, reducing reliance on multiple agencies and the gaps in accountability they create.
Pivotal's relevant capabilities include:

  • Secure, purpose-built fixtures: Bespoke POS and display solutions designed around product value, shopper access, and retailer requirements.
  • End-to-end delivery: Design, CAD, manufacture, and installation managed under one roof for consistent quality and clear responsibility.
  • Compliance assurance: Installations checked against agreed specifications, helping brands confirm that what was approved is what reaches the store.
  • Ongoing maintenance: Continued support that keeps displays intact and performing, with Pivotal's engineers having completed over 2,000 retail and brand installations in 2025 alone.

To strengthen how your products are protected and presented in store, contact Pivotal to discuss a tailored display and maintenance programme.
Through courage we choose innovation to keep our customers and their shoppers ready for tomorrows retail.
Explore our latest product innovations below ▾